Emkay Global Financial Recommends Buy on Varun Beverages with Target Price of Rs 625
Emkay Global Financial Services has maintained a bullish stance on Varun Beverages Limited (VBL), recommending a Buy rating on the stock with a revised target price of Rs 625 in its research report dated May 01, 2025. This target represents a projected upside, reflecting the company’s strong fundamentals and growth potential despite some short-term challenges.
View this post on Instagram
Strong Quarterly Performance, Domestic Growth Outperforms Expectations
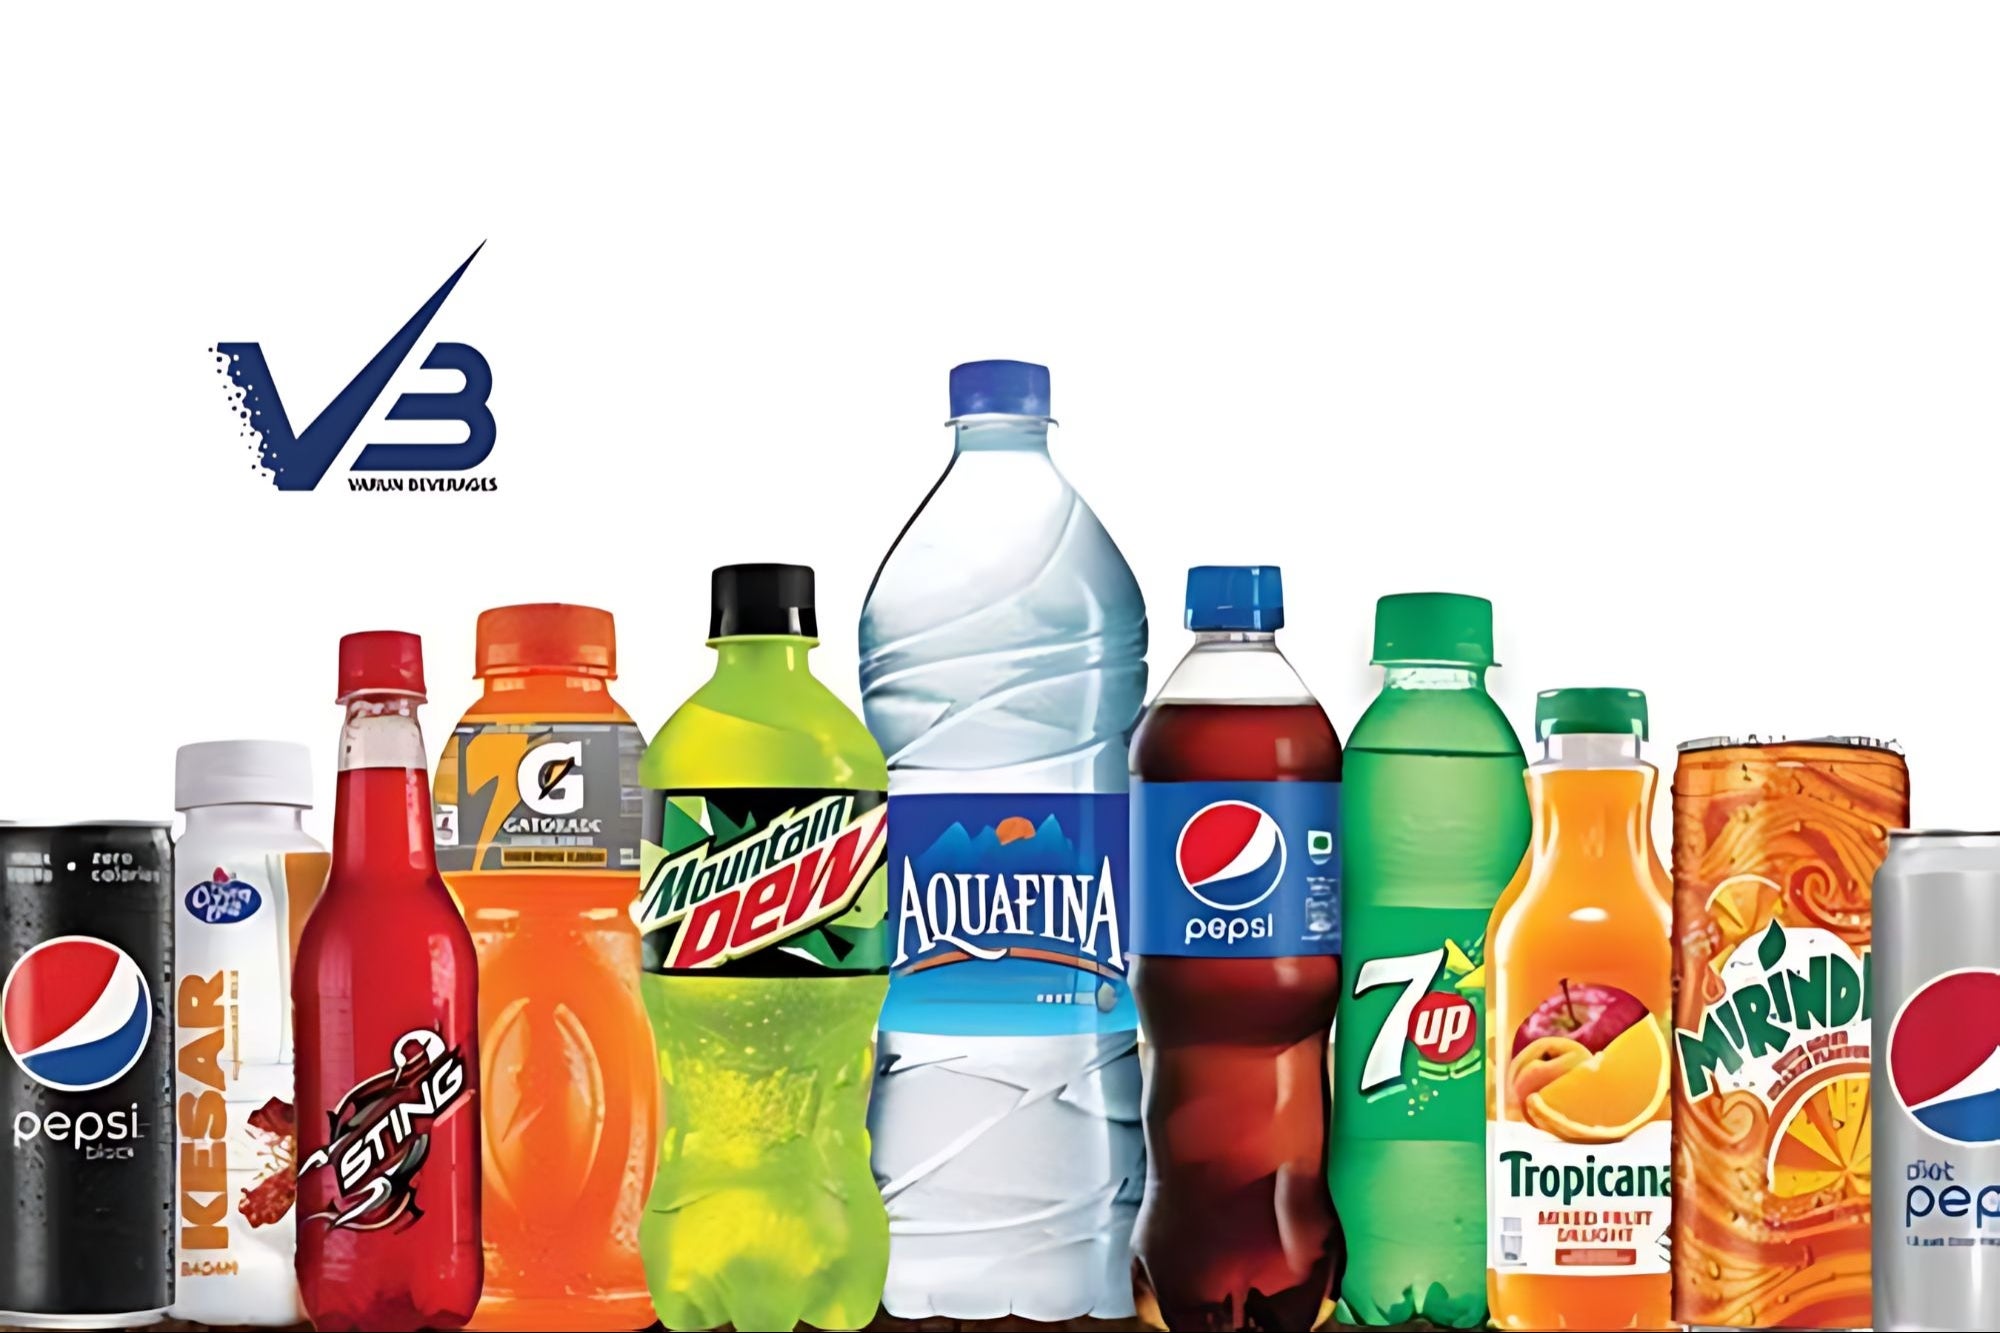
Varun Beverages, a leading bottler and distributor of PepsiCo products, reported a robust and largely in-line quarterly performance. The company recorded an 18% growth in India revenue, outperforming expectations of a 15% increase. This growth was driven by a solid 16% rise in volume and a 2% increase in realization. These figures underline the company’s stronghold in the Indian market, where demand for beverages continues to rise, aided by strategic initiatives and product diversification.
However, the company faced a slight challenge on the international front. International revenue realization dipped by approximately 12% due to the consolidation of the South African region, which has a lower revenue realization. Despite this, consolidated revenue growth remained solid at 30%, showcasing the company’s ability to maintain growth even in more competitive or lower-margin markets.
Challenges and Revised Earnings Estimates
The research report notes some ongoing challenges that slightly impacted VBL’s outlook. Persistent unseasonal rains in key markets during the peak season, combined with the scrapping of the Tanzania/Ghana acquisition, contributed to a 10-12% cut in EPS estimates. The Tanzania/Ghana markets had been expected to contribute around 7-8% of the topline, and the absence of these markets has temporarily dampened VBL’s earnings expectations.
Despite these headwinds, Emkay Global remains confident in the company’s long-term prospects. The research highlights that the company’s strong organic growth trends in Q1, combined with VBL’s competitive strategies and investments, position it well for future expansion. Emkay emphasizes that highly competitive intensity in the beverage sector is expected to accelerate the category’s growth, particularly in under-penetrated markets. VBL’s investments in Above the Line (ATL) and Below the Line (BTL) marketing strategies are designed to capture more market share, further driving revenue growth.
Focus on Margin Stability
While rising competition poses some risks to margins, Emkay Global remains optimistic about VBL’s ability to maintain healthy margins. The report points to VBL’s backward integration at its manufacturing plants, a shift toward low-calorie product mixes, and PET lightweighting as key factors that will help stabilize and potentially improve margins over time.
Moreover, the company’s strategy of product diversification, including healthier beverage options, aligns well with current consumer trends, which will further solidify its position in the market.
Outlook: Double-Digit Growth Forecast
Emkay Global Financial has a positive long-term outlook for Varun Beverages, forecasting a strong 15% revenue growth and a 20% EPS growth compound annual growth rate (CAGR) over the next three years (CY24-27E). The research report expects the company to continue outperforming the broader Fast-Moving Consumer Goods (FMCG) sector due to its strong brand portfolio, competitive pricing strategies, and operational efficiencies.
Despite the recent EPS revision and the challenges faced in international markets, Emkay maintains its Buy rating on Varun Beverages. The company’s ongoing investments in expanding its market reach and improving product offerings are expected to help drive growth and profitability in the coming years.
Conclusion
Varun Beverages continues to demonstrate resilience in the face of challenges, with a strong domestic performance and a growing international presence. While there have been some adjustments to earnings estimates, the company remains well-positioned to benefit from the ongoing expansion of the beverage category, particularly in emerging markets.
With a target price of Rs 625, Emkay Global’s recommendation underscores the strong growth prospects for Varun Beverages. Investors looking for long-term growth in the FMCG sector can consider Varun Beverages as a solid option, supported by its dominant market position, expanding product portfolio, and strategic focus on sustainability and competitive expansion.